Legal disclaimer
This article explains general Indian legal and banking information, reviewed on 9 October 2026. It is not advice for an individual dispute. Consult an advocate about the incident, loan, evidence and available remedies. Seek appropriate police assistance where there is an immediate threat.
Start with a lawful complaint, supported by records
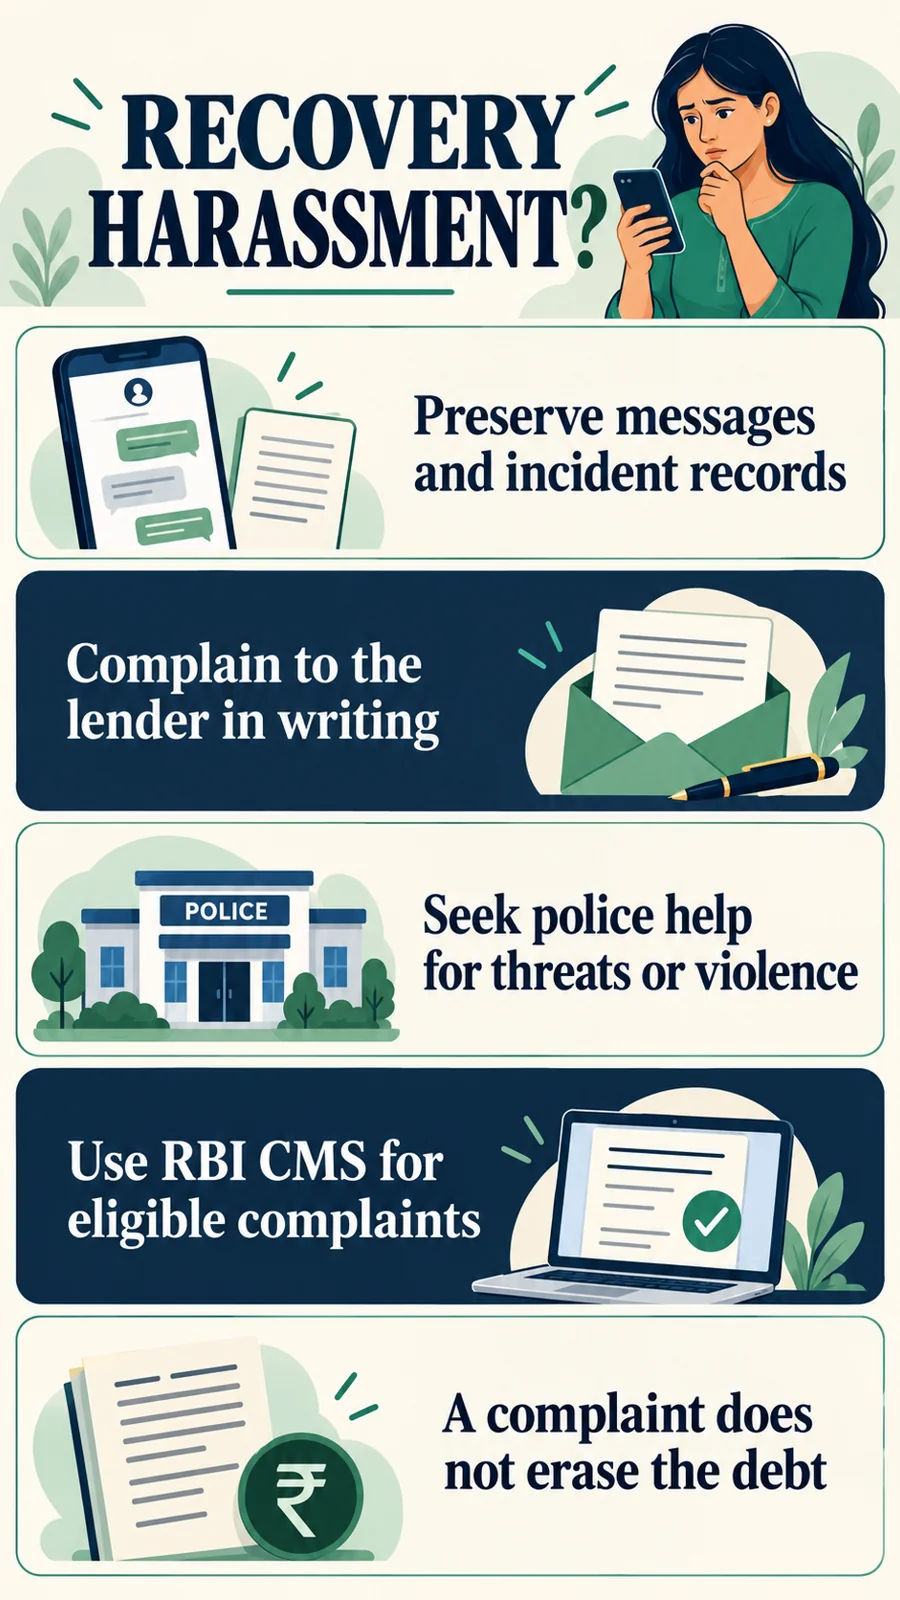
If a recovery agent threatens or humiliates you, the useful response is to preserve evidence, complain to the lender and seek police assistance where the facts disclose an offence. Violence, retaliation and invented allegations are not lawful remedies. An advocate can assess whether a legal notice or other proceedings would help. The purpose is to stop improper conduct and obtain appropriate relief through the correct process.
A harassment complaint does not erase a genuine debt. The lender may pursue legally available recovery, but that does not give an agent permission to intimidate borrowers or embarrass their families. Explain the conduct complaint separately from the repayment dispute. A clear account of what happened and what you want corrected is more useful than a general demand that the bank must stop all communication forever.
FACT: A caller’s threat of imprisonment is not a court order. Equally, do not dismiss a genuine summons or statutory notice as just another collection call.
Current RBI conduct rules
The Responsible Business Conduct Directions for commercial banks and NBFCs prohibit covered recovery practices such as intimidation, public humiliation, intrusion into family privacy and misleading representations. They also prohibit overdue-loan recovery calls before 8 a.m. and after 7 p.m. The linked 2025 directions were updated in July 2026. These particular provisions exclude microfinance loans, which have their own applicable framework. [1]
The permitted calling period is not permission to harass during those hours. Outsourcing does not allow the regulated lender to disclaim responsibility for agents’ conduct. Identify the actual bank or NBFC, rather than only the app or agency name. Different types of regulated entities have different instruments, and a private moneylender or unauthorised app is not automatically covered by the RBI Ombudsman scheme.
Identify the agent and the claimed authority
A legitimate repayment reminder or visit is not necessarily harassment. Ask for identification and authorisation, and verify the agency through the lender’s official channel. Keep the details of any notice shown to you. Do not give an agent an OTP, PIN or account password. A caller’s knowledge of your name and balance does not establish that a personal payment link is genuine.
An unsecured loan does not give an agent a general private power to attach household property. With a secured loan, the agreement, notices and lawful repossession process require separate examination. Avoid assuming that every repossession is theft or that every agent can take whatever property they want. If there is forced entry, violence or a threat to take belongings, prioritise safety and seek appropriate assistance.
Preserve evidence accurately
Write down the date, time, number, agent’s name, agency, words used and any witnesses. Preserve original messages and emails as well as useful screenshots. A screenshot alone may not answer questions about authenticity. Keep original files and the relevant device where practicable. Do not edit a recording or message to give it a meaning that the actual conversation did not have.
Call recordings raise separate privacy, authenticity and electronic-evidence questions. Do not assume that every recording is automatically admissible or publish private phone numbers to retaliate. Give an advocate the original file and explain how it was obtained. Submit relevant evidence to the appropriate authority, with only the personal information necessary for the complaint. Fabricated material can damage an otherwise legitimate grievance.
Complain to the lender in writing
Use the official grievance channel or nodal officer listed on the lender’s website, statement or app. Include the necessary account reference, a concise incident chronology, agent details and supporting records. Specify what you want: investigation of the agency, an end to abusive calls, authorised contact arrangements and a written response. Describe actual events rather than copy accusations that do not fit your experience.
Keep proof of submission and acknowledgement. If the balance is disputed, request a statement showing principal, interest, charges and payment credits. If you need revised instalments, send a realistic repayment proposal. A bank’s acknowledgement of a conduct complaint does not mean that it also authorised you to stop paying. Separate the issues so the lender can investigate each one clearly.
Escalation through RBI CMS
The Reserve Bank–Integrated Ombudsman Scheme, 2026 came into force on 1 July 2026. Eligible complaints about deficiencies in service can be submitted through https://cms.rbi.org.in. Complain to the regulated entity first. If it does not reply within thirty days, or a longer response period prescribed by applicable RBI/NPCI/card-network rules, or you are dissatisfied with the reply, check the remaining eligibility conditions. [2]
Clause 10 generally requires escalation within ninety days of expiry of the response period or the entity’s last communication, whichever is later. A grievance pending or decided on merits in another specified forum can affect maintainability. Earlier complaints have savings arrangements. A police complaint is not automatically identical to every excluded proceeding; examine its nature and the scheme rather than assume either automatic acceptance or automatic rejection.
When a police complaint is appropriate
Violence, forced entry, property damage or criminal intimidation can justify seeking police assistance depending on the facts. BNS Section 351 addresses criminal intimidation, but every unpleasant or forceful word does not establish that offence. The nature of the threat and the required legal elements matter. Describe what happened in your own words and let the authorities assess the applicable offences. [3]
BNSS Section 173 addresses information concerning cognizable offences. Electronic information has procedural requirements, including the required confirmation, that should be followed. Ask for acknowledgement and preserve what you submitted. Filing a complaint does not guarantee an FIR, arrest or compensation in every case. If appropriate action is not taken, an advocate can explain the available senior-police or magistrate route under the applicable procedure. [4]
What a legal notice can achieve
A notice through an advocate formally communicates the events, legal objection and requested action to the lender and relevant agency. It can ask for abusive contact to stop, for communication to follow authorised channels and for relevant records to be preserved. Include earlier complaint dates and supporting facts. The notice should fit your incident, rather than repeat a generic accusation of every possible offence.
A notice is not an injunction and does not automatically suspend repayment or litigation. Sending one is not a universal prerequisite for every complaint. Do not wait for a notice response where there is an immediate safety issue. An injunction, damages claim or consumer remedy may be considered where legally available, but forum, eligibility, evidence and the relief sought require individual assessment.
A relevant Supreme Court reference
Manager, ICICI Bank Ltd. v. Prakash Kaur, (2007) 2 SCC 711 is an important Supreme Court decision criticising strong-arm recovery tactics and emphasising procedures recognised by law. It should not be read as making every reminder a crime or every repossession invalid. The loan agreement, conduct and current rules must still be assessed against the specific circumstances.
Using a judgment’s name in an argument does not cancel the balance or authorise abuse of the agent. Explain the specific improper conduct and supporting evidence in your complaint. This gives the authority a real issue to investigate. A recovery dispute can involve both an obligation to repay and a right to protection from intimidation; one does not automatically remove the other.
Handle repayment discussions carefully
Ask for a written statement and an authorised payment channel. Make a proposal that reflects what you can realistically pay. Independently confirm any account or payment instruction through the lender. Avoid an unverified personal UPI transfer or cash payment without a receipt. A promised discount is not an approved settlement unless the authorised terms are documented and any required steps are completed.
If a meeting feels unsafe, request a bank or other appropriate setting and support from a trusted person. Do not escalate a confrontation. Tell someone you trust if repeated pressure is causing serious distress. A practical combination of documented complaints, lawful assistance and honest repayment communication is more useful than trying to handle intimidation secretly or making commitments that you cannot fulfil.
Frequently asked questions
Can I stop EMIs after submitting a harassment complaint?
The complaint itself is not a moratorium or stay. Revised terms require an authorised agreement or appropriate order.
Are all evening phone calls prohibited?
The rule discussed concerns covered overdue-loan recovery calls outside the specified hours. Identify the purpose, entity and applicable directions.
Can an agent publicly shame my family?
Public humiliation and intrusion into family privacy are prohibited practices in covered recovery. Preserve records and complain in writing.
Does a legal notice close a recovery case?
No. A notice is formal communication. An existing case or court order needs to be addressed through its own procedure.
Can every loan app complaint go to RBI CMS?
No. Check the underlying lender, scheme coverage and grievance eligibility. Unauthorised lending or criminal conduct can require another route.
Advice
Put safety first, preserve accurate evidence, complain clearly to the lender and keep repayment discussions in writing. Seek police help where criminal conduct is involved. Use RBI CMS and legal notices within their actual conditions. A genuine complaint seeks lawful action against improper recovery; false allegations and claims that the debt has vanished can make the dispute harder to resolve.
Related reading: Can credit card company file police case? Civil dispute reality vs illegal recovery threats · How to settle loan with bank for less amount: One-Time Settlement (OTS) procedure and credit impact
Official sources
[1] RBI — Commercial Banks Responsible Business Conduct Directions, paragraph 445: https://rbidocs.rbi.org.in/rdocs/notification/PDFs/170MD.PDF ; NBFC Directions, paragraph 100: https://rbidocs.rbi.org.in/rdocs/notification/PDFs/362MD26CA543937BA439A97E1BCFC08CF5808.PDF
[2] RBI — Integrated Ombudsman Scheme, 2026, announcement with official scheme link: https://www.rbi.org.in/Scripts/BS_PressReleaseDisplay.aspx?prid=62052 ; complaints: https://cms.rbi.org.in
[3] Ministry of Home Affairs — BNS, Section 351: https://www.mha.gov.in/sites/default/files/2024-04/250883_english_01042024.pdf
[4] Ministry of Home Affairs — BNSS, Section 173: https://www.mha.gov.in/sites/default/files/2024-04/250884_2_english_01042024.pdf
Detailed legal disclaimer
This educational content does not endorse violence, retaliation, fabricated allegations, debt evasion or disregard of court orders. The facts and current law determine available remedies. No FIR, arrest, compensation, debt waiver or platform-policy approval is guaranteed. Seek individual legal advice before acting. This disclaimer does not remove statutory rights, contractual obligations or legal responsibilities.