Legal disclaimer
This article provides general information about Indian law and banking complaints, reviewed on 9 October 2026. It is not individual legal or financial advice. Consult an advocate about notices or proceedings and discuss repayment options directly with the lender.
Can police arrest someone for an unpaid personal loan?
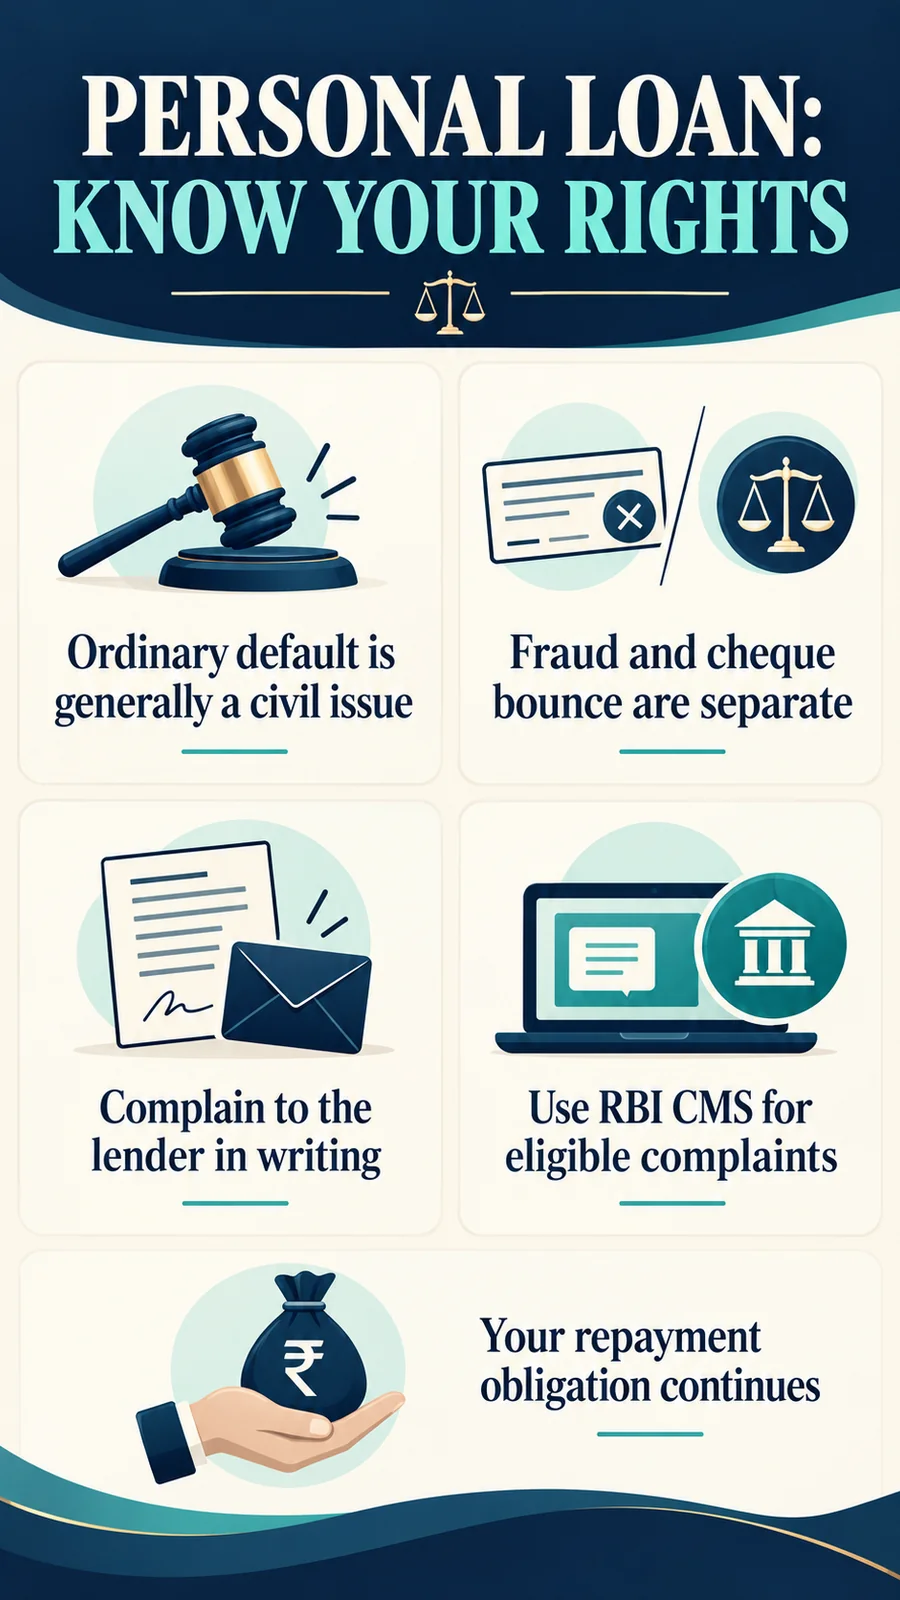
Ordinary inability to repay a personal loan is generally a civil recovery issue. Missing an EMI does not, by itself, authorise a recovery agent to have a borrower arrested. However, this does not erase the debt or mean that every dispute involving a loan is purely civil. Alleged fraud, forged documents, cheque dishonour and disobedience of judicial directions can raise separate legal issues.
A borrower should therefore distinguish a collection threat from a genuine police or court document. Check the sender, account and case details independently. Preserve the notice and obtain advice instead of ignoring it. The correct response to financial distress is a documented repayment discussion and timely participation in lawful proceedings, not hiding assets, making false statements or disappearing from contact.
FACT: Protection against harassment does not cancel repayment obligations. A collection agent cannot exercise the powers of a police officer or a court merely because a loan is overdue.
Default and fraud are different questions
A later loss of income or inability to pay does not automatically establish cheating. Section 318 of the Bharatiya Nyaya Sanhita deals with cheating; the required deception and dishonest inducement must be assessed against the facts. The statute itself distinguishes a dishonest intention at the relevant initial stage from a later breach of a transaction entered into honestly. Fabricated income or identity documents can materially change the legal position. [1]
For conduct before 1 July 2024, the earlier IPC and applicable transitional rules may remain relevant. Do not assume that renaming an allegation under BNS proves it or that describing a matter as “civil” prevents investigation of a genuine offence. If police contact you, verify the communication, obtain advice and cooperate through the proper process. A recovery representative’s claim that an FIR exists should be independently checked.
Cheques and payment mandates need separate attention
A cheque issued toward repayment can create a Section 138 Negotiable Instruments Act issue if it is dishonoured and the legal requirements are met. That complaint has its own notice and filing process. An unpaid loan balance and a cheque prosecution are related financially but are not interchangeable legal procedures. Do not issue a cheque you cannot honour merely to end a difficult collection call.
A failed electronic payment mandate can also require separate analysis under the relevant law and facts; it should not automatically be treated as either a criminal case or a harmless missed transfer. Preserve return messages and any statutory notice. If there is already a case, an informal restructuring conversation with the bank may not change court deadlines. Ask what documents and orders are required to record a resolution.
What civil recovery may involve
Depending on the agreement, lender and available forum, recovery can involve a civil suit, arbitration or another legally available process. Read any arbitration notice and check whether you can challenge the claim, charges, jurisdiction or appointment procedure. Do not assume that every personal loan goes to the same tribunal or that a private notice has the force of a court decree.
After a valid decree or enforceable award, execution can involve attachment through legal process, subject to exemptions and other conditions. “Unsecured” means the particular loan lacks agreed collateral; it does not mean that lawful recovery after adjudication is impossible. An agent cannot simply seize household property as if a personal loan gave a general private power of attachment. Obtain advice if someone claims that authority.
Civil detention is not automatic either
Section 51 CPC contains safeguards for detention in execution of a money decree, including an opportunity to show cause and recorded judicial satisfaction of the statutory conditions. Mere inability to pay should not be equated with automatic imprisonment. At the same time, a blanket statement that an unpaid civil debt can never involve detention is inaccurate; means to pay coupled with refusal and specified bad-faith conduct can be relevant. [2]
Jolly George Varghese v. Bank of Cochin, (1980) 2 SCC 360, is a significant Supreme Court authority distinguishing poverty from the conditions necessary for civil detention. Its principle supports the need for a lawful assessment, not immunity from execution. Keep truthful records of present means and pressing financial needs, and respond to any execution notice through an advocate.
Recovery agents must follow conduct rules
RBI’s current Responsible Business Conduct Directions for commercial banks and NBFCs prohibit intimidation, public humiliation, invasion of family privacy, threatening or anonymous calls and misleading representations in covered overdue-loan recovery. They also prohibit recovery calls before 8 a.m. and after 7 p.m. The regulated lender remains responsible for its outsourced agents. These particular provisions exclude microfinance loans, which have separate applicable rules. The linked directions are the 2025 instruments updated in July 2026. [3]
The permitted calling period is not permission to harass during those hours. Keep messages, numbers, dates and the words used. Ask the lender to identify the authorised agency and agent. Avoid physical confrontation or threats in response. If there is violence, criminal intimidation or an immediate safety issue, contact police through the appropriate channel; a banking complaint and a criminal complaint address different concerns.
First complain to the lender
Send a concise written complaint to the lender’s designated grievance officer or authorised complaint channel. Include the loan account reference, incident chronology, supporting messages and the remedy requested. Explain whether the issue is harassment, an unexplained charge, an incorrect balance or a payment not credited. Keep proof of submission and acknowledgement, and do not send unrelated identity or financial information to an unverified caller.
Continue the repayment discussion separately. You can dispute an abusive call while acknowledging an undisputed balance. Ask for a current statement showing principal, interest, charges and credits. Do not treat a complaint receipt as a moratorium or assume that RBI will stop all collection while your complaint is pending. A change to payment terms needs an authorised agreement or relevant order.
RBI Ombudsman: the current 2026 rules
The Reserve Bank–Integrated Ombudsman Scheme, 2026 took effect on 1 July 2026. New complaints must be assessed under its eligibility rules rather than copied from older 2021 guides. Earlier complaints, related appeals and awards are subject to the scheme’s savings arrangements. RBI’s Complaint Management System is at https://cms.rbi.org.in. Check that the entity and service fall within the scheme’s coverage. [4]
Complain to the regulated entity first. If no reply arrives within thirty days, or the longer response period specified by applicable RBI/NPCI/card-network rules, or you are dissatisfied with the response, examine eligibility for escalation. Clause 10 generally requires filing within ninety days from expiry of that response period or the entity’s last communication, whichever is later. Check all conditions, including prior proceedings on the same grievance; this is not a universal deadline for every legal remedy. [4]
What RBI complaints cannot promise
The scheme concerns qualifying deficiencies in service. It does not guarantee a loan waiver, a settlement percentage or fresh credit. Matters involving a lender’s commercial decision have exclusions, and the same grievance pending or decided in another specified forum can affect maintainability. Use the scheme to explain an eligible service problem accurately rather than ask it to cancel a valid debt solely because repayment is difficult.
The complaint process is cost-free under the scheme. Avoid intermediaries promising guaranteed deletion of a loan or credit entry for a fee. A disputed balance, correction of reporting and voluntary settlement are different issues. Keep copies of the complaint, lender’s response and the documents relevant to the particular problem. Do not delay court or arbitration action while waiting for an Ombudsman complaint to be assessed.
Restructuring or settlement: ask, do not assume
If circumstances have changed, write to the lender with an honest explanation and a realistic repayment proposal. Ask about tenure changes, revised instalments or a settlement that the lender is willing and authorised to offer. There is no automatic right to a discount or EMI holiday simply because you request it. Compare the total payable and charges, not only the size of the next instalment.
Before paying a negotiated settlement, obtain written terms from an authorised source. They should identify the account, amount, due dates, treatment of remaining dues, and closure documentation. Settlement may affect future borrowing and credit reporting; “settled” and “closed after full repayment” can have different implications. Request accurate reporting and check it afterwards, without assuming that a settlement removes truthful history immediately.
Frequently asked questions
Can an agent arrest me for three missed EMIs?
An agent has no arrest power. Genuine police or court action must have a separate lawful basis and should be addressed promptly.
Is my family automatically liable?
Relationship alone is not enough. A co-borrower, guarantor or person who undertook a legal obligation may have different liability.
Does complaining to RBI cancel interest?
No automatic cancellation follows from filing. The applicable contract, rules and any relief granted determine the position.
Can the bank file a case?
The lender can pursue legally available recovery. Whether a criminal allegation is sustainable depends on additional facts and law.
Should I borrow from another app to pay this EMI?
Assess the total cost and affordability carefully. Replacing distress with higher-cost debt may worsen the problem; a lender discussion and independent advice can be more useful.
Practical next steps
Prepare a budget, request the loan statement, preserve notices and propose an affordable payment plan in writing. Document harassment and follow the current complaint route. Seek an advocate promptly for police contact, statutory notices, arbitration or court proceedings. Your rights help ensure lawful recovery; responsible communication and accurate records help you manage the continuing debt.
Related reading: How to reduce maintenance amount in court: Legitimate grounds to challenge interim alimony · How to avoid jail in cheque bounce case: Section 138 NI Act defenses and settlement rules
Official sources and legal references
[1] Ministry of Home Affairs — BNS, Section 318: https://www.mha.gov.in/sites/default/files/2024-04/250883_english_01042024.pdf
[2] India Code — CPC, Section 51 and Order XXI; see also Jolly George Varghese v. Bank of Cochin, (1980) 2 SCC 360: https://www.indiacode.nic.in/bitstream/123456789/2191/1/eng.pdf
[3] RBI — Responsible Business Conduct Directions, 2025, updated July 2026: Commercial Banks, paragraph 445: https://rbidocs.rbi.org.in/rdocs/notification/PDFs/170MD.PDF ; NBFCs, paragraph 100: https://rbidocs.rbi.org.in/rdocs/notification/PDFs/362MD26CA543937BA439A97E1BCFC08CF5808.PDF
[4] RBI — launch of the Integrated Ombudsman Scheme, 2026, with official scheme link: https://www.rbi.org.in/Scripts/BS_PressReleaseDisplay.aspx?prid=62052 ; RBI-issued scheme copy hosted by Axis Bank, Clauses 10 and 20: https://application.axis.bank.in/docs/Integrated_Ombudsman_Scheme%202026.pdf
[5] RBI Complaint Management System: https://cms.rbi.org.in
Detailed legal disclaimer
This educational material does not encourage deliberate default, document fraud, hiding assets, avoiding service or disobeying judicial orders. Legal and financial consequences depend on the facts, agreement and current rules. No waiver, settlement discount, credit-score outcome, platform-policy approval or immunity is guaranteed. Seek individual advice before acting. This disclaimer does not cancel contractual or statutory obligations.