You sold crypto through a P2P platform, received a bank transfer and released the asset. Days later, your UPI payments or ATM withdrawals stop working. The bank says a cybercrime complaint has led to an account restriction. The payment you treated as an ordinary sale may have been traced to money lost by a fraud victim.
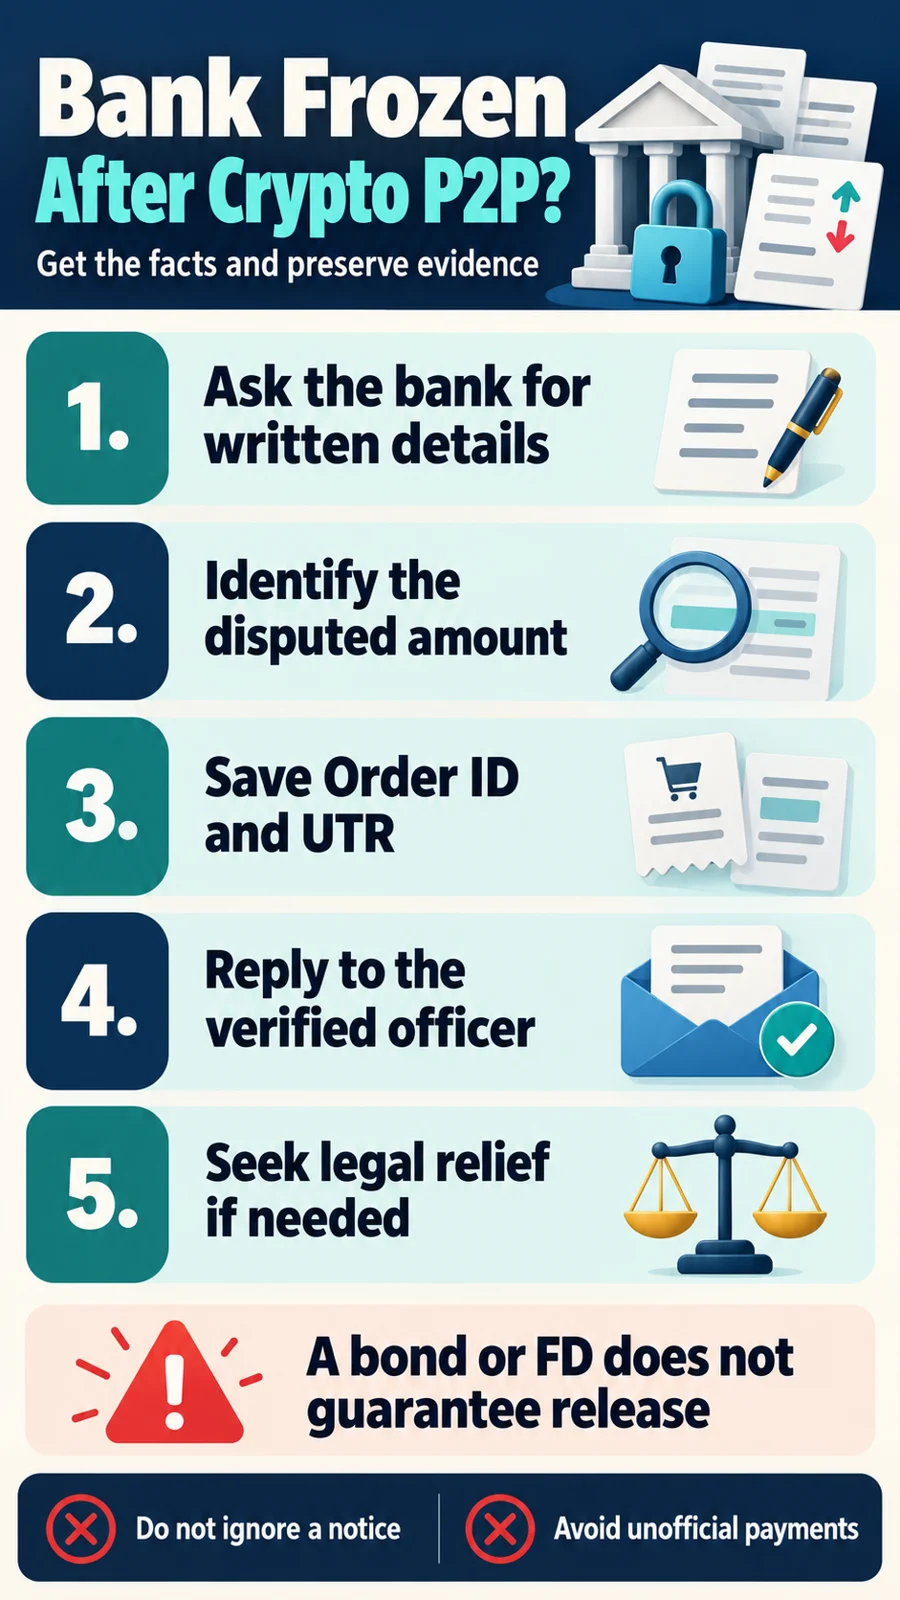
If your bank account is frozen after crypto P2P, start with written restriction details and a complete transaction trail. Saying you are innocent, showing a platform order or submitting an indemnity bond does not automatically release the account. You can request appropriate relief, including preservation of an identified disputed sum while allowing access to other funds, but the outcome depends on the actual order, investigation and applicable procedure.
How can a P2P payment enter a fraud investigation?
A platform connects buyers and sellers, while the rupee payment may arrive directly from a bank account. Even when the platform buyer appears verified, the payer can be a different person. If a victim’s money passes through several accounts before reaching yours, your incoming credit may become part of the investigation.
Your delivery of crypto is relevant evidence. It does not independently establish that the rupees came from a legitimate source. For example, imagine receiving ₹15,000 for crypto in an account already holding ₹5 lakh. A complaint concerning that credit does not, by itself, answer whether the entire balance should remain restricted. Equally, it does not establish that holding only ₹15,000 must always be sufficient. These figures are illustrative: identify the orders and transactions first.
Does being “Layer-3” prove innocence?
The word layer describes a position in a transaction chain. It is not a statutory certificate excluding a person from investigation. The trade purpose, payer identity, platform conversation and onward transfers matter alongside distance from the original transaction. Explain the actual events rather than relying on a layer number as a guaranteed defence.
Ask the bank for these details in writing
- The restriction type: a complete debit freeze, an amount-specific lien or hold, or a separate KYC/compliance restriction.
- The date imposed, identified disputed amount, relevant credit date and UTR/reference.
- The requesting agency, police station/state, requisition reference and available official investigating officer contact.
- The FIR/NCRP complaint reference or requisition copy, where available and legally shareable.
- Whether several complaints or orders affect the same account.
If investigation-related information cannot be fully disclosed, ask for the available details and the reason for any refusal. Keep the written acknowledgment and bank grievance number. A verbal statement from the branch is a weak foundation for deciding the next step. Our general cybercrime bank account freeze guide explains the broader process.
If family accounts are restricted, document each separately
A parent or spouse’s account should not be assumed to be covered by the same restriction merely because of the relationship. Each account holder should ask their own bank for its specific basis. An onward transfer from your sale, a joint account, or a separate disputed credit creates different facts to explain.
List every affected account, complaint reference and requesting agency. Record why money moved between family members and preserve genuine supporting evidence. Relief for one account will not necessarily remove another bank’s separate restriction. Do not conceal ownership or transactions, or create new transfer chains to move money beyond a hold.
Build a P2P evidence packet
- The platform order ID, trade date/time, crypto asset and quantity, agreed rupee amount and completion record.
- The counterparty profile and verification information actually visible to you. Do not invent information about the buyer.
- The complete chat/export and payment instructions, especially any mismatch between buyer and bank payer.
- The bank statement showing the credit, UTR, payer information and relevant onward transfers.
- The crypto release record and wallet address/transaction hash where available.
- Genuine purchase, sale or tax records relevant to the transaction, if held and requested. A GST invoice is not a universal requirement for every individual P2P sale; never manufacture one.
Keep original exports as well as screenshots. Prepare a dated summary linking the platform order, incoming credit and asset release. Do not post PAN details, full account numbers or another person’s private data in public forums. Provide necessary records to a verified authority and retain proof of submission.
Responding to police: documents and attendance are different
Verify the notice and officer through an official channel, then address the stated requirements within the deadline. A caller’s number or private UPI address is not proof of police identity. Verification is not a reason to disregard a genuine notice’s response date.
The document-production provision under old CrPC Section 91 has its counterpart in BNSS Section 94. The new law’s commencement and saving provisions for existing proceedings mean a notice should not be rejected solely because it mentions an older section. A document request and a direction requiring personal attendance raise different issues. Emailing an affidavit is not automatically compliance with every attendance requirement.
If travel to another state is difficult, request time or an appropriate alternative arrangement in writing and seek an acknowledgment. Do not assume remote participation has been approved. Have a lawyer review the actual notice and applicable provision where necessary. See our guide to police calls and notices for the broader distinctions.
Can a full freeze be limited to the disputed amount?
In a representation, identify the transaction and amount disclosed by the bank and explain which other funds remain inaccessible. Request clarification from the relevant authority and consideration of an amount-specific restriction where permitted by the applicable order and law. Attach genuine evidence of salary, pension, rent or medical needs if relevant.
It is inaccurate to declare every full-account freeze automatically unlawful. Multiple complaints, alleged proceeds of crime, mixing of funds and the nature of the order can affect the result. Removing one complaint-related hold may leave another in place. A bank cannot simply be expected to cancel a binding agency or court direction itself.
Court relief: the actual role of a bond or fixed deposit
Identify the order and proper jurisdiction before selecting a remedy. BNSS provisions concerning seizure and attachment of proceeds of crime are distinct; every bank restriction cannot be assigned the same section. In an applicable property-seizure situation, BNSS Section 503 may provide a route to seek an appropriate Magistrate’s order. Older proceedings and other situations may require a different applicable remedy.
A lawyer can frame a request to preserve the disputed amount while allowing access to other funds, or seek removal of the restriction where justified. A court may consider conditions such as a bond, undertaking or deposit. Creating an FD or sending an indemnity bond does not establish an automatic entitlement. Claims of same-day release without examining jurisdiction, the complaint and local applicable judgments are unreliable.
A concise request you can adapt for the bank
My account ending [XXXX] has had a debit restriction since [date]. Please provide the restriction type, available complaint/requisition reference, requesting agency contact, disputed transaction/UTR and amount in writing. I am ready to submit records of the relevant P2P trade. Where permitted by the applicable order and law, please consider access to the remaining balance while preserving the disputed sum, and obtain clarification from the relevant authority. Please acknowledge this request and issue a grievance reference.
For the investigating officer, add the order ID, credit date, UTR and a factual trade explanation with numbered attachments. Explain what the documents establish. Avoid absolute assertions such as “I delivered crypto, so repayment can never arise.” Review the response in light of your particular legal position.
I4C, banking complaints and requests for repayment
I4C’s official public notice explains that NCRP complaints are investigated by the relevant State/UT law enforcement agencies. The decision to lien-mark or freeze an account is taken by the relevant investigating officer or bank under the applicable framework. An email asking NCRP/I4C to unfreeze an account therefore does not replace action before the appropriate authority.
A bank grievance can address service deficiencies; an RBI complaint does not automatically overturn a police or court order. Do not make unofficial payments to a private UPI account for a supposed settlement, processing fee or bribe. Obtain a verified written basis and legal advice for any legitimate recovery or settlement. Paying money alone does not guarantee removal from every complaint or release of all affected accounts.
Frequently asked questions
The buyer was platform-verified. Is that sufficient?
It is part of your evidence, not a guarantee that the payment source was legitimate. Match the payer, bank credit and trade records as well.
Will returning the disputed amount automatically unfreeze the account?
No. The relevant authority’s decision, all active restrictions and the lawful settlement process still matter.
Is PAN, an affidavit and a GST invoice a mandatory standard checklist?
Requests depend on the case. Supply genuine identity and transaction records; do not rely on a universal checklist or create false documents.
Is there a guaranteed 48-hour release?
No universal release deadline or success guarantee applies to these situations. Written details and a complete evidence packet make the next step clearer.
Our advice
Identify the bank restriction in writing, preserve the full P2P record and respond appropriately to the verified officer. Explain your essential banking needs and seek relief based on the actual disputed sum and order. Serious notices, multiple states or a prolonged full freeze deserve a lawyer’s review.
General information, not individual legal advice. The applicable process depends on the notice, order, law and case facts. Reviewed: 13 October 2026. Images are illustrative.