Builder delayed possession: can you stop paying the bank EMI?
You are paying rent, the purchased flat remains unfinished and the lender demands monthly instalments. The builder promised to pay until possession but has stopped responding. Cancelling auto-debit is not a complete solution. Examine the housing loan and subvention documents, reconcile payments and seek relief through a written lender arrangement or an order that actually covers your case.
The direct answer is that delayed possession does not automatically cancel or suspend your bank loan. Builder obligations, potentially improper disbursal and borrower repayment are separate issues. Relief may be available on suitable facts, but neither a DRT application nor a High Court petition guarantees an EMI or credit-reporting stay for every homebuyer.
Immediate checklist
- Obtain the signed loan agreement, sanction and repayment schedule.
- Collect builder-buyer and tripartite agreements, amendments and brochures.
- Record the promised possession date, builder-paid EMI period and last payment.
- Request release dates, amounts, authorisations and construction-stage verification.
- Identify deadlines in any default, possession or auction notice immediately.
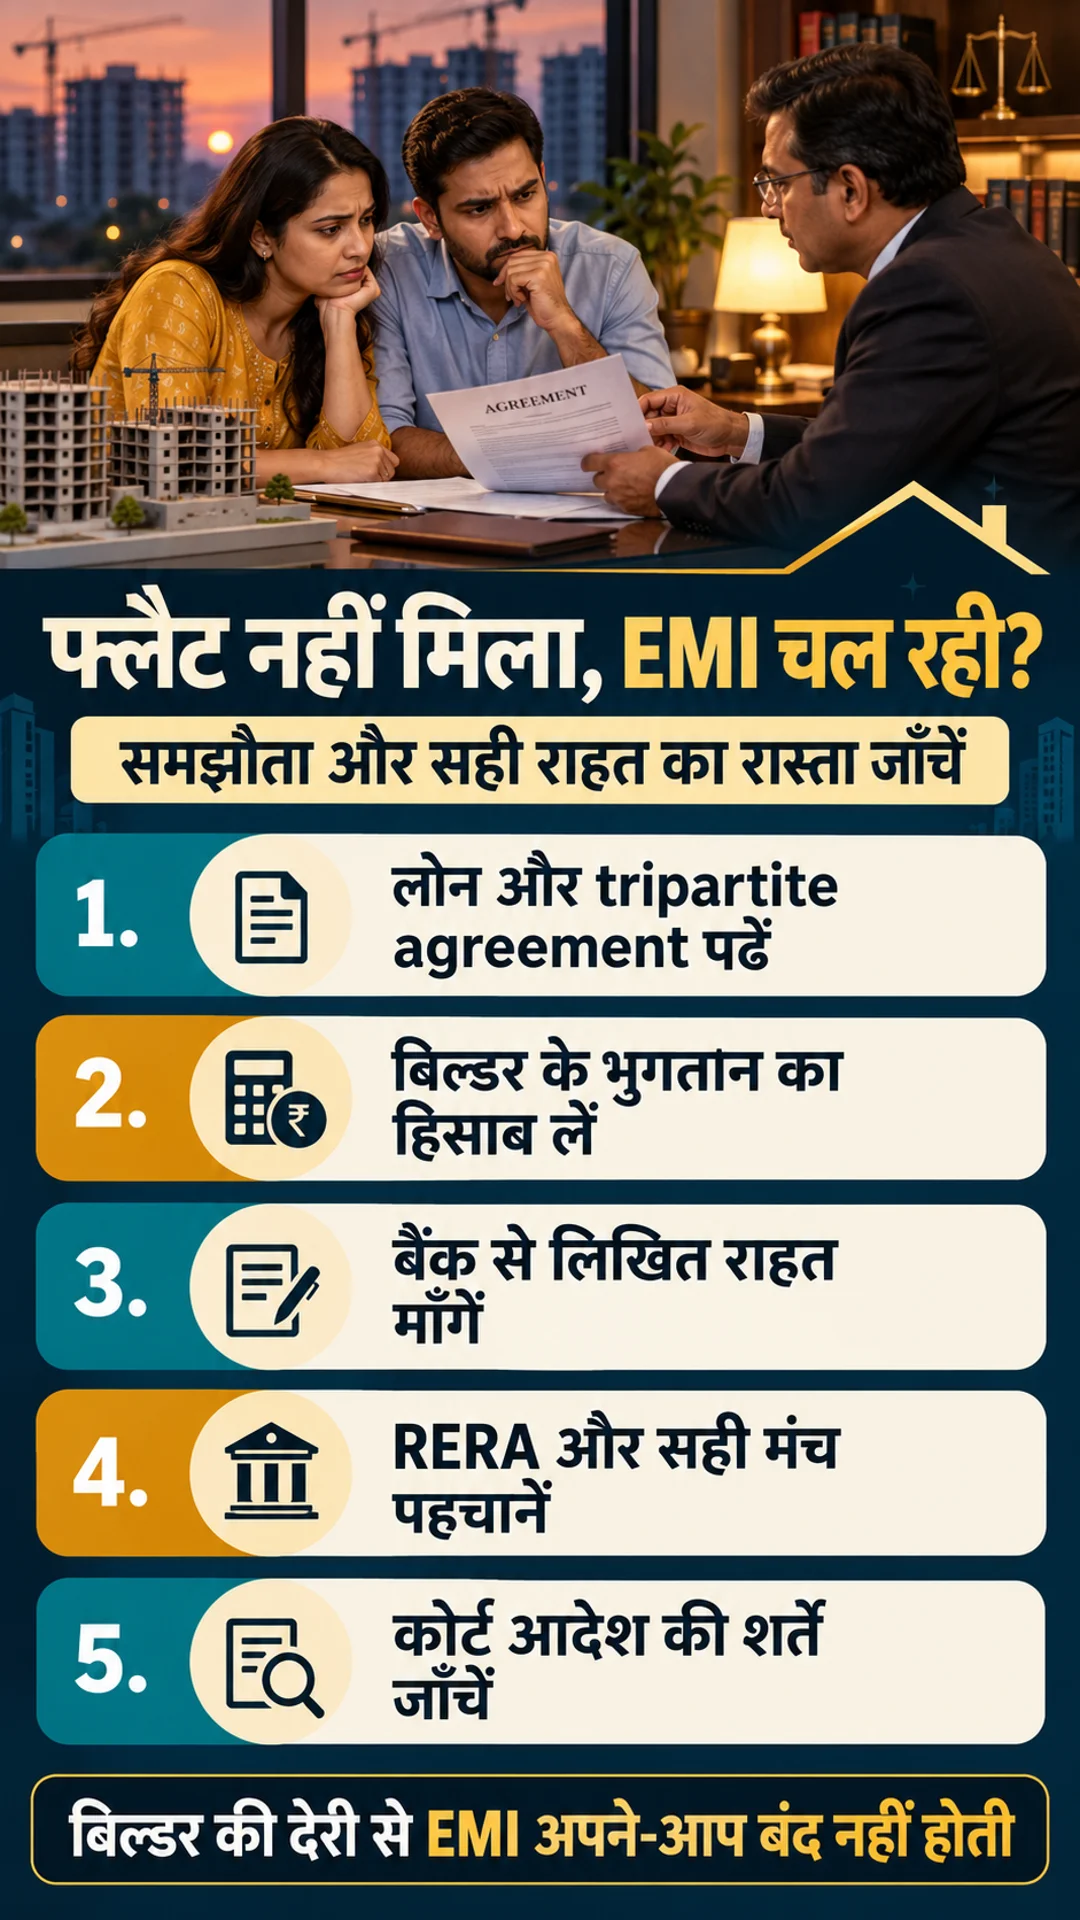
Subvention, pre-EMI and the tripartite agreement
Under a subvention arrangement, the developer may promise to service EMI/pre-EMI on a loan in your name for a fixed period or until possession. A bank/HFC, builder and buyer may sign a tripartite agreement. This is not the same as a government interest subsidy or debt waiver. Preserve the “no EMI till possession” advertisement, but also examine signed terms and actual payments.
Pre-EMI generally refers to interest on the disbursed amount; full EMI can include principal repayment. The starting dates and conversion depend on your documents. Separate the amount released by the lender, payments credited from the builder and arrears now attributed to you. A sanction amount is not necessarily the amount already disbursed.
For example, a ₹40 lakh sanction with ₹25 lakh released needs a calculation based on the actual loan history. Do not assume interest on the entire sanction is correct merely because that amount appears in the sanction letter. Request reconciliation of dated releases, principal balances and charges. This is an illustration, not a calculation of your actual EMI.
Mark these clauses
- Does the builder’s payment promise end on a date, possession or another milestone?
- What happens to borrower liability if the builder defaults?
- What construction-stage and borrower-consent conditions govern releases?
- Who receives a cancellation refund and how is the lender paid?
- What do grace periods, dispute clauses and later amendments change?
Why construction-linked disbursal and RBI rules matter
RBI housing-finance guidance has identified risks in upfront builder-linked schemes. Its official 2015 Master Circular required individual housing-loan releases to be linked closely to construction stages and advised against upfront disbursal for incomplete private projects. It also contained a conditional exception for government/statutory projects. These distinctions matter when reviewing how your lender released funds.
Examine the rules applicable at the time and the lender category. A commercial bank, HFC, regional rural bank and co-operative bank should not be treated as interchangeable without checking their framework. Quoting an old circular does not itself erase a debt. Connect any alleged breach to dated releases, your authorisation, construction progress and the applicable agreement.
Ask which builder demand supported each release, what stage was verified and what consent was relied upon. Compare available site records and RERA filings with the payment schedule. Request investigation of specific discrepancies rather than making unsupported allegations of fraud or collusion. Preserve unanswered requests or refusals so the disputed record can be examined later.
Before stopping EMI: default, credit reporting and written relief
Stopping payment without lender approval or an applicable order may create arrears, charges, adverse reporting and recovery exposure. Cancelling a mandate changes the payment mechanism; it does not terminate the loan. A complaint against the builder is not automatically a bank moratorium. Keep any disagreement over liability separate from the immediate payment position.
If rent and EMI together are unaffordable, submit a truthful income-expense statement and request temporary relief, restructuring or a repayment review. Ask for the period, interest, revised instalment, charges and credit-report treatment in writing. A telephone assurance to “look into it” is not permission to stop paying. A modified arrangement can increase total interest or extend the term.
FACT: do Supreme Court subvention orders cover everyone?
The Supreme Court has examined homebuyer grievances and bank-builder conduct in Himanshu Singh and connected subvention proceedings. Official orders dated 29 April 2025 and 20 January 2026 illustrate the importance of agreements, payments, project status and recovery records. They should not be described as a nationwide EMI waiver for all unfinished flats.
Your lawyer must identify the covered parties, project, lender, duration and conditions, and check subsequent orders. A restriction on coercive recovery, the obligation to pay instalments, interest accrual and credit reporting are distinct questions. Protection on one issue does not automatically provide relief on all four. Filing an intervention or petition is also not equivalent to receiving an operative order.
RERA, consumer commission, DRT or High Court?
For promoter delay, RERA section 18 is significant. Subject to its conditions, withdrawing allottees may seek return of amounts with prescribed interest and compensation in the statutory manner; those continuing may seek delay interest. Check section 31 complaint procedure and state rules. Relief against the promoter does not automatically rewrite the housing-loan repayment schedule.
A consumer complaint about deficiency or unfair practices may be appropriate depending on consumer status, jurisdiction, limitation and the facts. Avoid overlapping claims seeking double recovery of the same loss. Disclose previous proceedings, settlements and builder insolvency, and coordinate the requested relief. The correct forum is determined by the legal issue, not simply by which portal looks easiest.
DRT is not a general counter for every request to stop EMI because a flat is late. SARFAESI section 17 generally addresses challenges to secured-creditor measures under section 13(4). Its statutory 45-day period is important; have the triggering action and deadline examined promptly. An ordinary EMI reminder is not automatically the same procedural stage as a possession or auction measure.
High Court writ maintainability depends on the lender, challenged action, alternative remedies and circumstances. A contractual dispute involving a private bank/HFC is not automatically suitable for a direct writ. Seek specific interim relief before the appropriate forum with supporting facts; filing alone does not grant a stay. Do not wait through a routine grievance cycle if a possession or auction deadline requires urgent legal action.
Your document file and two adaptable letters
Create a chronological index of allotment, agreements, sanction, release dates, receipts, possession promises, project records and notices. Keep the RERA registration number and publicly available progress filings. Avoid sharing PAN, identity documents or full account details in public groups. These samples are general requests, not filed court pleadings, and must be adapted to truthful facts.
1. Lender request for records and an interim arrangement
To: Branch Manager / Grievance Officer, [lender]
Subject: Loan [last four digits] – delayed project and subvention review
Sir/Madam,
My housing loan concerns [project/unit]. Agreement dated [date], clause [number], required the builder to service EMI/pre-EMI until [period/event]. The agreed possession date was [date]; current status is [facts with evidence]. Builder payments stopped on [date].
Please provide the loan statement, arrears/charge breakup, disbursal records, authorisations and available construction-stage verification. Kindly review [specific discrepancy] in the enclosed records.
In view of my documented income, rent and essential expenses, please review a suitable temporary repayment arrangement and communicate interest, charges and credit-report treatment in writing. Please investigate any inaccurate reporting or payment allocation and correct verified errors.
This letter does not unilaterally suspend EMI or claim that the loan is extinguished. [Attach any applicable order.]
Name, contact, date; attachments
2. Builder request for contractual dues and possession/refund position
To: [builder legal/customer-care office]
Subject: Unit [number], agreement [date] – subvention dues and delayed possession
Sir/Madam,
Clause [number] records your EMI/pre-EMI commitment for [period/event] and the agreed possession date is [date]. Since [date], the payment/construction position has been [facts]. Please provide reconciliation of outstanding contractual dues, payment evidence and a realistic completion/possession plan.
[State the chosen request as appropriate: possession with applicable delay relief, or review of withdrawal/refund.]
For a loan-funded refund, please clarify adjustment with the lender and treatment of any remaining loan balance.
Please respond within [reasonable period]. I reserve my available legal remedies.
Name, contact, date; relevant documents
If the lender does not respond, use its grievance escalation process. RBI CMS coverage, prior lender complaint and applicable waiting periods must be checked; not every HFC or contractual claim is covered identically. Pending proceedings and excluded commercial decisions can affect maintainability. An ombudsman complaint should not be presented as an automatic EMI-stay order.
What to give the lawyer seeking interim relief
- Chronology, signed clauses and lender correspondence.
- The specific action to restrain: recovery, auction, disputed debit or reporting.
- Evidence of urgent harm and the notice deadline.
- Existing proceedings/orders, payments and settlement proposals.
- The requested duration/conditions and relationship to final relief.
Advice and frequently asked questions
Advice
Keep the builder-delay claim and bank account reconciliation together. Do not stop instalments merely because a social-media group recommends it. Read written terms before accepting a new arrangement. If a refund is awarded or paid, confirm lender adjustment and closure/NOC: a refund order against the builder is not the same as closure of your loan account.
Does delayed possession automatically make EMI unlawful?
No. Review the agreements, releases, applicable rules and orders.
Does the builder’s promise mean I can never be asked to pay?
The commitment period, borrower liability and facts matter. Builder default does not automatically release the borrower.
Does filing RERA stop bank recovery?
Not by itself. Examine lender obligations and the exact scope of any interim order.
Can every stalled-project buyer obtain an EMI stay from DRT?
No. The tribunal’s jurisdiction and recovery stage must first be established.
Will a court stay erase CIBIL entries?
Check the order and the reporting facts. Dispute inaccurate entries with the lender and credit bureau using documents; do not assume every stay orders deletion of all records.
- RBI housing finance Master Circular 2015: historical disbursal guidance
- RERA Act: sections 18 and 31
- Supreme Court subvention proceedings: 29 April 2025
- Supreme Court subvention proceedings: 20 January 2026
- Supreme Court: section 17 SARFAESI remedy, 10 April 2024
- RBI complaint portal
Disclaimer: General legal and financial information for India. Agreements, lender category, state rules and proceedings affect outcomes. Fact-checked: 13 October 2026. No guarantee of EMI stay, refund, compensation or credit-score improvement.